Bonding Capacity: How Your WIP Schedule Determines It
Your bonding capacity is the single most important financial metric for a growing contractor. And your WIP Schedule is the document that determines it. Here's how it works.
What Is Bonding Capacity and Why Does It Matter?
Bonding capacity is the maximum amount of surety bonds a surety company will issue to your construction company. It's the single most important metric for a growing contractor — without bonding capacity, you can't bid on most commercial, industrial, or institutional projects.
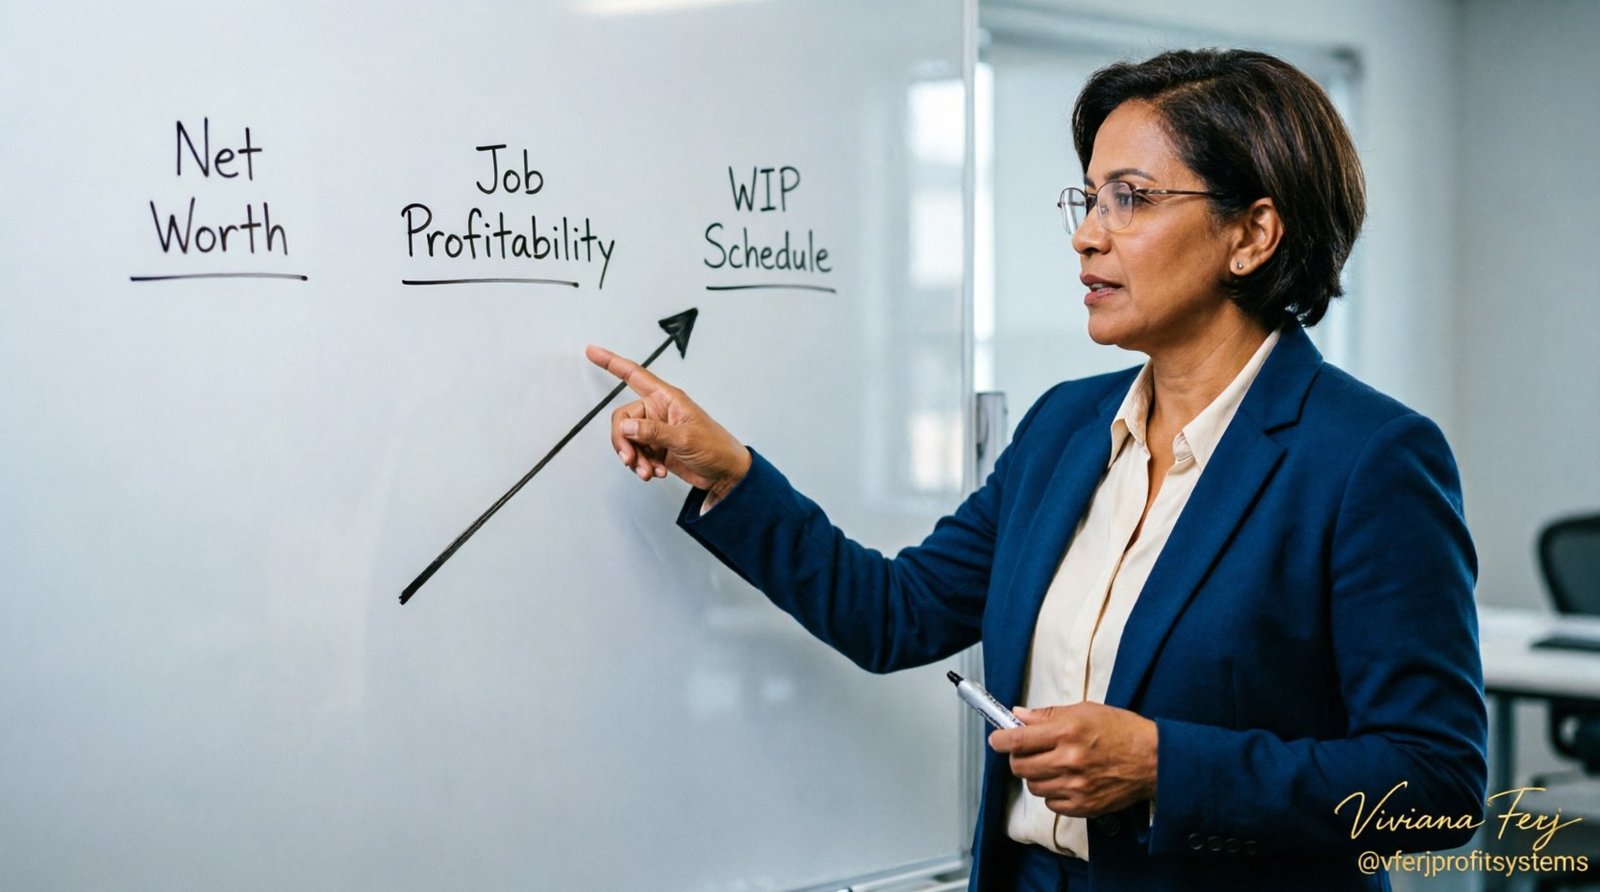
Bonding capacity is determined by a combination of factors: your net worth, your working capital, your job profitability, and — most importantly — the quality and consistency of your WIP Schedule.
The Three Factors That Determine Bonding Capacity
- Factor 1 — Net worth and working capital: Sureties typically require a certain amount of working capital relative to your contract backlog. A common benchmark is 5% to 10% of your annual volume.
- Factor 2 — Job profitability: Sureties look at your job margins — both historical and current. Consistent job profitability signals that you know how to manage projects.
- Factor 3 — WIP Schedule quality: This is where most contractors get tripped up. A clean, consistent WIP Schedule tells the surety that you have real control over your projects.
Why Your WIP Schedule Is the Most Important Document
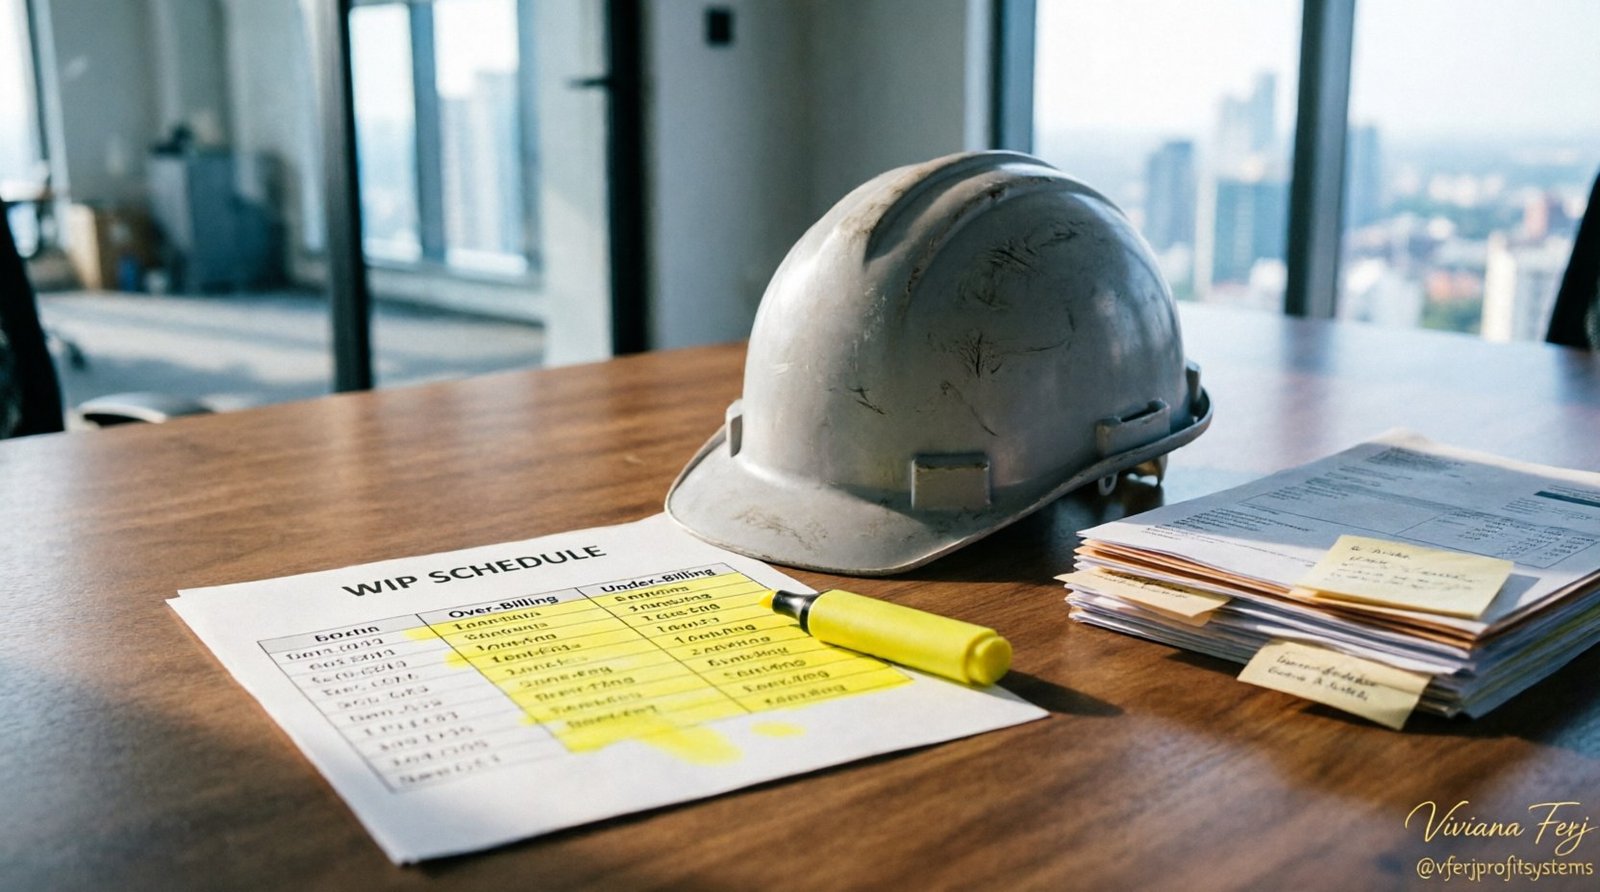
When a surety reviews your WIP Schedule, they're looking for three things:
- Consistency: Is the WIP Schedule prepared monthly, without gaps? A gap signals a lack of discipline.
- Accuracy: Do the job margins in the WIP Schedule match your financial statements? Inconsistencies are red flags.
- Over/Under-Billing: Are your jobs balanced, or are you consistently over-billed or under-billed? Both extremes are concerns.
A Numerical Example: How a Clean WIP Increases Bonding Capacity
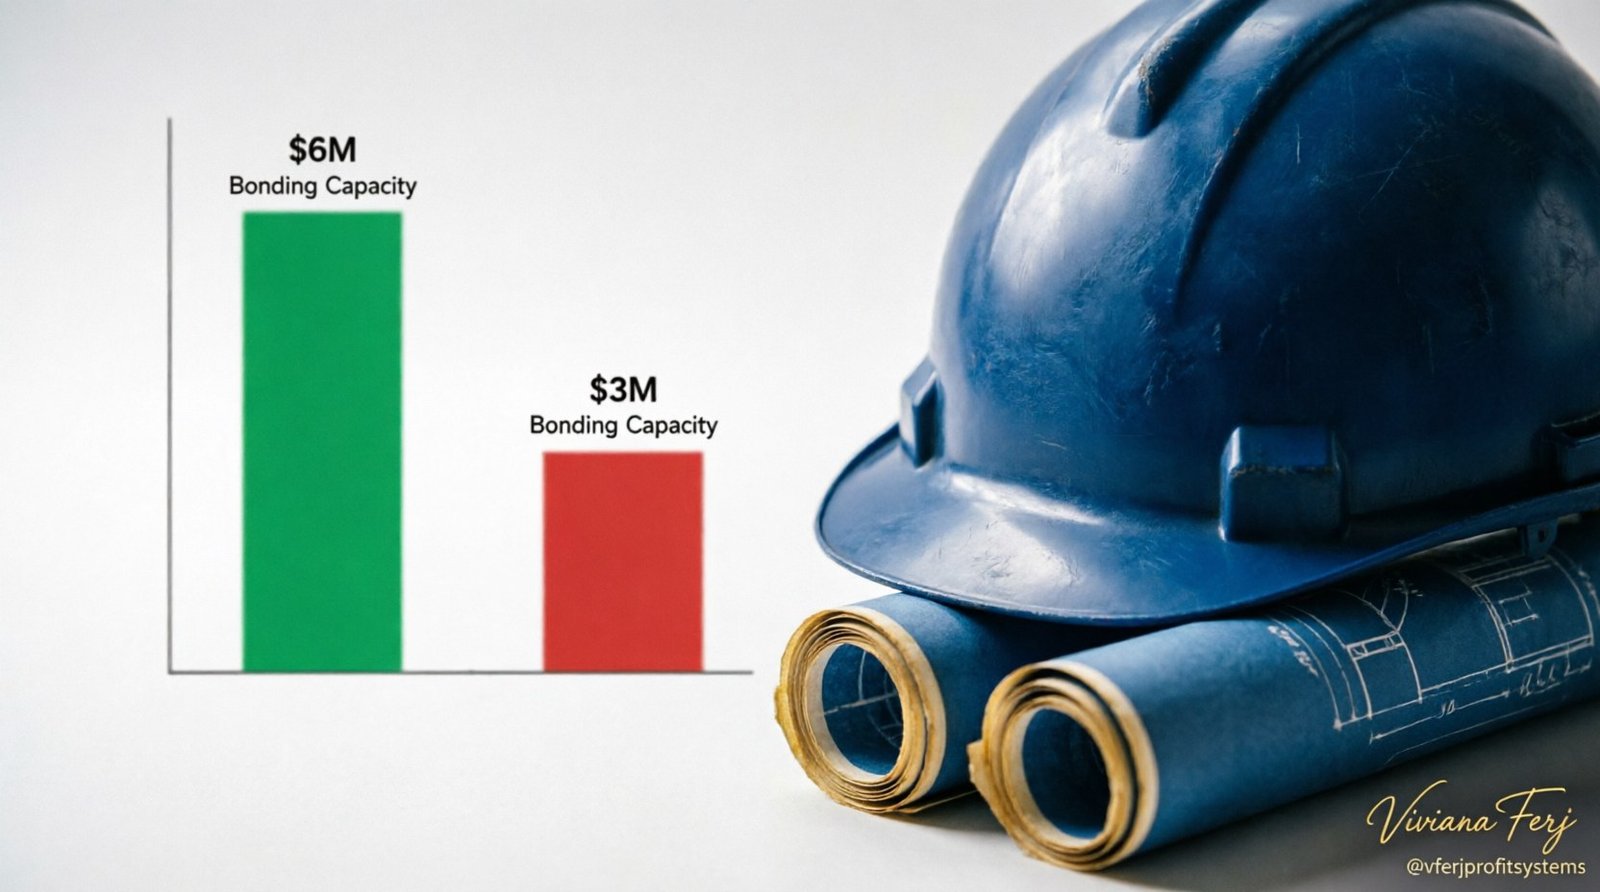
Suppose two contractors have identical net worth and working capital — $2 million each. Both generate $10 million in annual revenue.
Contractor A has a clean, monthly WIP Schedule with consistent job margins, balanced over/under-billing, and no significant profit fade. The surety grants bonding capacity of $6 million.
Contractor B has an inconsistent WIP Schedule — it's prepared quarterly at best, and job margins fluctuate wildly. The surety grants bonding capacity of $3 million — half of Contractor A's capacity.
Same financials, different bonding capacity — because the surety trusts Contractor A's numbers more.
How to Improve Your Bonding Capacity
- Prepare a clean WIP Schedule every month: No gaps. No excuses. Every month, without fail.
- Review job margins with your PMs: Don't let profit fade go unnoticed. Catch it early and correct it.
- Keep your job costing system accurate: Your WIP Schedule is only as good as your job costing.
- Maintain healthy working capital: Reduce AR, manage retainage, and keep your cash flow under control.
- Build a relationship with your surety: Share your WIP Schedule and financials proactively — don't wait for them to ask.
The Warning Signs Sureties Look For
- Gaps in the WIP Schedule: Missing months suggest you're not reviewing your jobs regularly.
- Inconsistent job margins: If margins fluctuate wildly, it suggests poor estimating or poor job management.
- High over-billing: Consistent over-billing suggests you're borrowing from the future — a risk to the surety.
- High under-billing: Consistent under-billing suggests cash flow strain — which can affect your ability to complete projects.
- Unbilled change orders: If change orders aren't being billed, you're eroding your margin.
Frequently Asked Questions
What is a typical bonding capacity multiplier?
Sureties typically grant bonding capacity of 5 to 10 times your working capital, depending on your track record and WIP Schedule quality.
Can I increase my bonding capacity quickly?
Not quickly — it takes time to build a track record. But improving your WIP Schedule consistency and job margins will increase your capacity over time.
What happens if I exceed my bonding capacity?
You can't. The surety will not issue bonds beyond your capacity. Exceeding your capacity means you can't bid on new work until you increase it or finish existing projects.
Do sureties look at personal credit?
Yes, for smaller contractors. Personal credit history is a factor in bonding decisions.
Take This to a Full Diagnostic of Your Operation
- Real profitability per job, not just company-wide
- WIP Schedule and detection of bonding issues
- Tax provision and multi-state exposure
- Bonding capacity and subcontractor risk
Get These Insights Straight to Your Inbox
A new article on construction finance every month — no spam, unsubscribe anytime.