Cash Flow Forecasting for Construction Companies
Cash flow is the lifeblood of a construction company. A cash flow forecast is the tool that helps you see gaps ahead of time and make decisions that keep your company solvent.
Why Cash Flow Forecasting Is Not Optional
Most construction companies don't fail because they're unprofitable — they fail because they run out of cash. Profit is a feeling. Cash is a fact.
A cash flow forecast is the tool that shows you when cash is coming in and going out. It tells you whether you'll have enough cash to pay your bills next month, or whether you'll need to draw on a line of credit. Without it, you're operating blind — and hoping that everything works out.
The Three Components of a Cash Flow Forecast
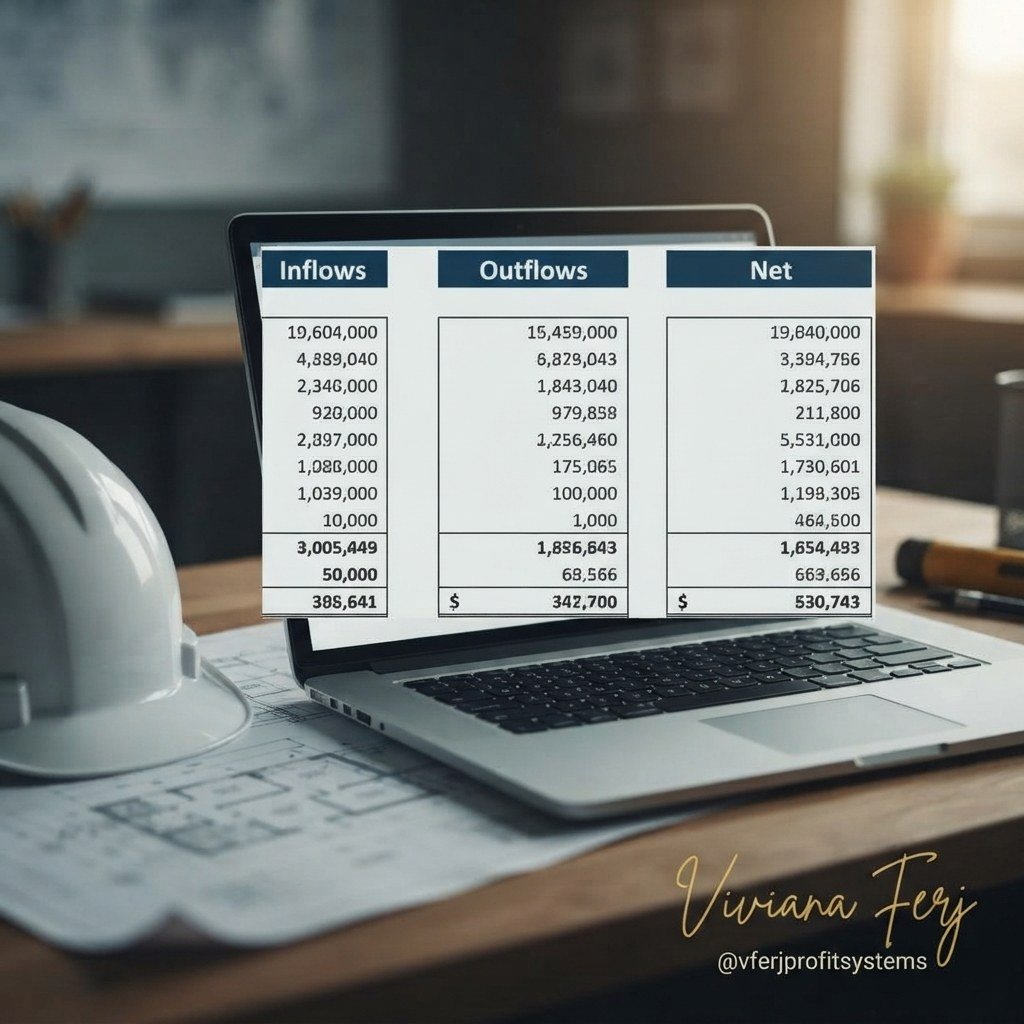
- Cash inflows: Progress billings, change orders, retainage releases, and any other sources of cash.
- Cash outflows: Payroll, subcontractor payments, material purchases, equipment rentals, overhead, taxes, and debt service.
- Net cash flow: The difference between inflows and outflows — positive or negative — over a given period.
How to Build a Cash Flow Forecast (Step-by-Step)
- Step 1 — Start with your WIP Schedule: Your WIP Schedule tells you what revenue you've earned and what you've billed. That's the foundation of your forecast.
- Step 2 — Estimate future progress billings: Based on your WIP Schedule and project schedules, estimate what you'll bill in each future month.
- Step 3 — Estimate cash collections: Not all billings are collected immediately. Apply your average collection period to your progress billings.
- Step 4 — Estimate future costs: Based on your job budgets and procurement schedules, estimate when you'll pay for materials, labor, and subcontractors.
- Step 5 — Calculate net cash flow: Subtract outflows from inflows for each month.
- Step 6 — Adjust for working capital needs: If your net cash flow is negative for multiple months, identify the gap — and plan how to cover it.
The Most Common Cash Flow Gaps in Construction
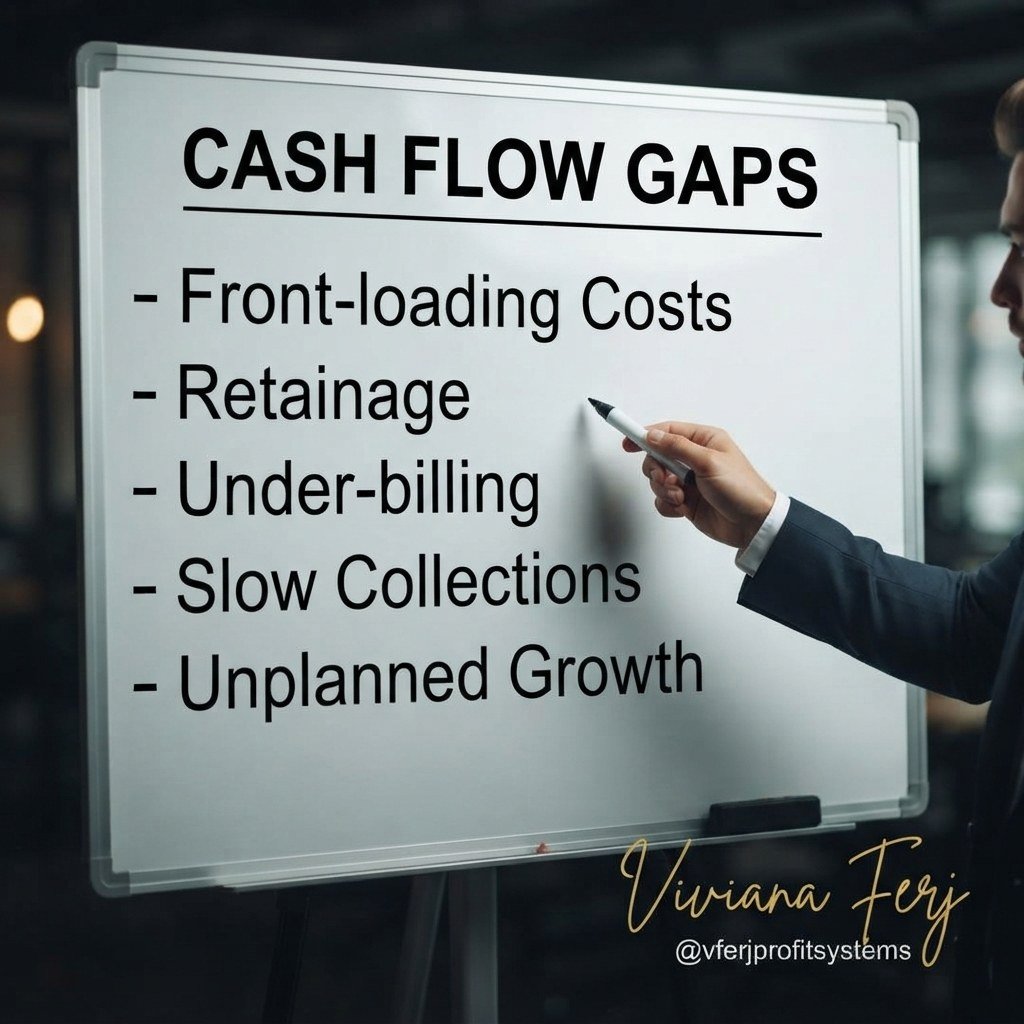
- Gap #1 — Front-loading costs: You pay for materials and mobilization before you receive your first progress payment.
- Gap #2 — Retainage: Money you've earned but can't access until project completion.
- Gap #3 — Under-billing: Work performed but not yet billed.
- Gap #4 — Slow collections: Clients pay late, and you're financing their delay.
- Gap #5 — Unplanned growth: Taking on more work than your working capital can support.
How to Manage Cash Flow Gaps
- Use a line of credit: Draw on it during cash flow gaps and pay it down when cash comes in.
- Negotiate better payment terms: Ask clients for shorter payment cycles — or offer discounts for early payment.
- Negotiate supplier terms: Ask suppliers for extended payment terms to match your billing cycle.
- Factor your receivables: Sell your receivables to a factor for immediate cash, at a discount.
- Reduce overhead: Review your overhead costs and cut anything that doesn't directly support your operations.
Cash Flow Forecasting and Bonding Capacity
When a surety evaluates your bonding capacity, they look at your cash flow history and forecasts. A consistent ability to generate positive cash flow signals financial discipline. A history of cash flow strain — or no forecast at all — is a red flag.
Frequently Asked Questions
How far ahead should I forecast?
At minimum, 3 to 6 months. Some contractors forecast 12 to 18 months, especially on long-duration projects.
How often should I update my forecast?
Monthly, in sync with your WIP Schedule and financial statements. Some contractors update weekly during periods of rapid growth or cash flow strain.
What's the difference between a cash flow forecast and a budget?
A budget is a plan for revenue and expenses. A cash flow forecast is a plan for when cash actually comes in and goes out. They're different — and you need both.
Can I use Excel for cash flow forecasting?
Yes — Excel works for small companies. As you grow, consider specialized cash flow forecasting software that integrates with your accounting system.
Take This to a Full Diagnostic of Your Operation
- Real profitability per job, not just company-wide
- WIP Schedule and detection of cash flow gaps
- Tax provision and multi-state exposure
- Bonding capacity and subcontractor risk
Get These Insights Straight to Your Inbox
A new article on construction finance every month — no spam, unsubscribe anytime.