Job Costing 101: The Foundation Every Contractor Should Master
Job costing is the single most important accounting system in construction. Without it, you can't track profitability per job, build a reliable WIP Schedule, or qualify for bonding. Here's what you need to know.
What Is Job Costing — And Why Does It Matter?
Job costing is the accounting system that tracks costs and revenue for each individual project. Unlike a retailer who tracks costs by product category, a construction company tracks costs by job — because every job is different.
Job costing matters because it's the only way to answer the most important question in construction: "Is this job making money?" Without job costing, you only know your company-wide profitability — which tells you nothing about which jobs are carrying the weight and which ones are dragging you down.
The Three Components of Job Costing
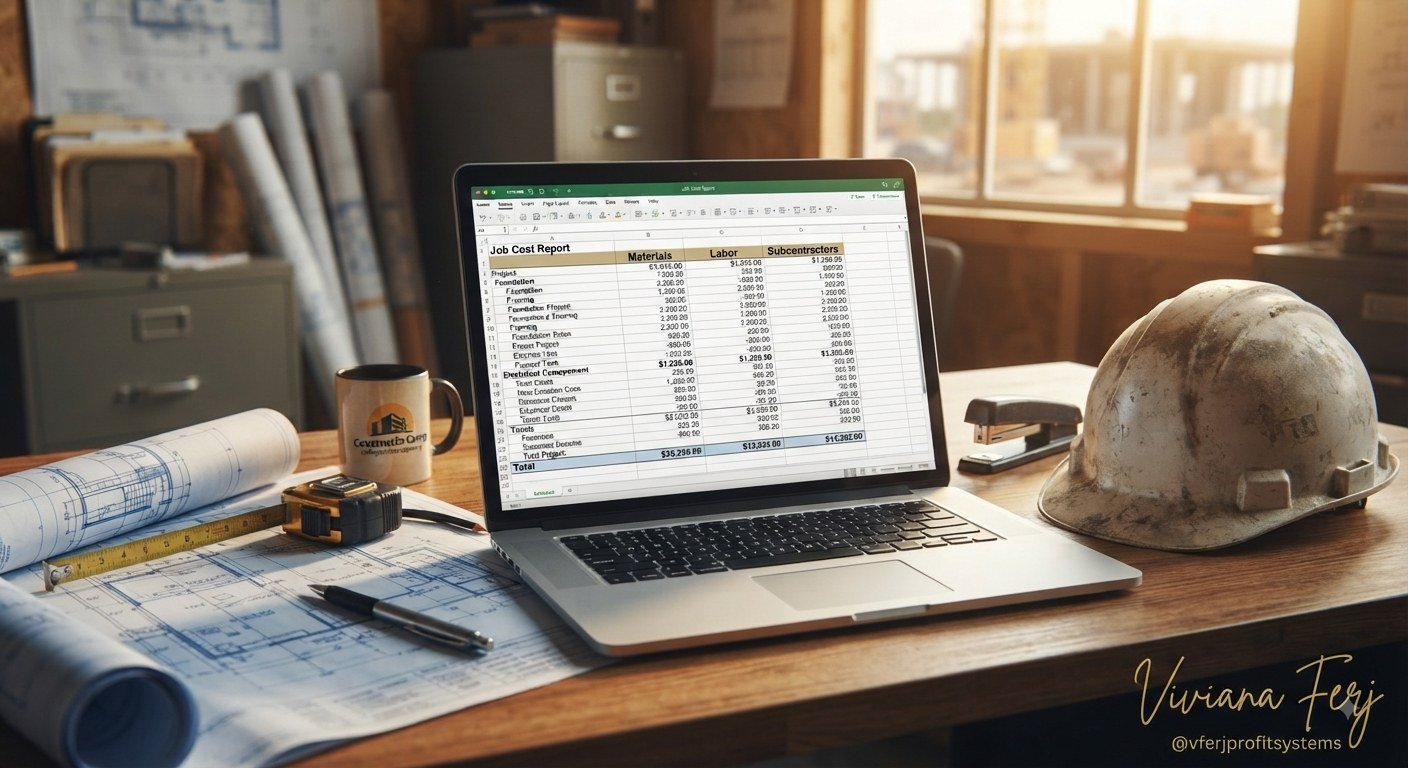
Every job cost system tracks three categories:
- Materials: Everything that goes into the physical structure — concrete, steel, lumber, wiring, fixtures.
- Labor: Wages for direct labor on the job — carpenters, ironworkers, equipment operators.
- Subcontractors: Payments to specialty trades — electricians, plumbers, HVAC, drywall.
These are direct costs. They can be traced directly to a specific job. Indirect costs — like superintendent salaries, job site trailers, and small tools — are allocated separately.
How to Set Up a Job Costing System
Setting up job costing is simpler than most contractors think. Here's the step-by-step:
- Step 1 — Create a job number for every project: Every job gets a unique identifier in your accounting system.
- Step 2 — Set up cost codes: Break each job into cost categories — excavation, concrete, steel, electrical, etc. — and assign each a code.
- Step 3 — Track costs by job and cost code: Every invoice, every timesheet, every equipment charge is coded to a specific job and cost code.
- Step 4 — Track revenue by job: Every invoice to the client is coded to the same job number.
- Step 5 — Run job cost reports monthly: Compare actual costs and revenue to your budget for each job.
The 3 Most Common Job Costing Mistakes
- Mistake #1 — Not tracking costs by cost code: A job total is useful, but it won't tell you why you're over budget. Cost codes tell you whether it's materials, labor, or subcontractors.
- Mistake #2 — Allocating indirect costs inconsistently: If you allocate superintendent costs to some jobs but not others, your job profitability numbers aren't comparable.
- Mistake #3 — Waiting until the job is over to review costs: Job costing is a real-time tool. Reviewing it at closeout is too late to fix anything.
How Job Costing Connects to Your WIP Schedule
Your WIP Schedule is built from job cost data. The costs incurred to date come directly from your job costing system. The estimated total cost comes from your budget. The earned revenue is calculated from the percent complete — which is driven by costs incurred compared to estimated total cost.
If your job costing system is inaccurate, your WIP Schedule is inaccurate. And if your WIP Schedule is inaccurate, you can't rely on your over/under-billing position, your job margins, or your bonding capacity.
Job Costing and Bonding Capacity
When a surety company evaluates your bonding capacity, it looks at your WIP Schedule — and your WIP Schedule is only as reliable as your job costing system. A consistent, accurate job costing system tells a surety that you have real control over your projects.
An inconsistent job costing system — or no job costing system at all — tells a surety that you don't really know which jobs are making money and which ones aren't. That's a risk signal, and it can reduce your bonding capacity, even if your company-wide financials look healthy.
Job Costing and Taxes
Under the percentage-of-completion method, taxable income is calculated based on costs incurred and revenue earned. That calculation depends entirely on accurate job costing. If your costs aren't tracked correctly by job, your taxable income will be wrong — and you could end up paying too much tax, or worse, triggering an audit.
Frequently Asked Questions
What software should I use for job costing?
Most contractors use specialized construction accounting software — Foundation, Viewpoint, Sage, or Procore. QuickBooks can work for smaller contractors, but it has limitations for complex job costing.
How often should I review job costs?
At minimum, monthly — in sync with your WIP Schedule. Some contractors review job costs weekly on large or high-risk projects.
What's the difference between job costing and project management?
Project management tracks schedules, scope, and quality. Job costing tracks dollars. They're complementary — you need both to run a successful construction company.
Can I do job costing in Excel?
You can, but it's difficult to scale. Excel works for a few jobs, but as you grow, you'll need a proper accounting system to handle the volume.
Take This to a Full Diagnostic of Your Operation
- Real profitability per job, not just company-wide
- WIP Schedule and detection of losing jobs
- Tax provision and multi-state exposure
- Bonding capacity and subcontractor risk
Get These Insights Straight to Your Inbox
A new article on construction finance every month — no spam, unsubscribe anytime.