Multi-State Tax Exposure: The Silent Risk
If your construction company works in more than one state, you're exposed to multi-state tax risk. Here's what you need to know to protect yourself from surprises.
The Hidden Tax Liability on Every Out-of-State Project
If your construction company operates in more than one state, you're exposed to multi-state tax risk. And most contractors don't realize it until they receive a tax notice from a state they barely remember working in.
The problem is simple: each state has its own tax rules, filing requirements, and definitions of what creates a tax obligation. What's legal in Texas may not be legal in California — and the penalties for non-compliance can be significant.
What Creates a Tax Obligation? The Concept of Nexus
Nexus is the legal term for a connection to a state that creates a tax obligation. In simple terms, if you have enough presence in a state, you may owe state income tax, sales tax, or other taxes there.
In construction, nexus can be created by:
- Physical presence: Having an office, a job site, employees, or equipment in the state.
- Economic presence: Having a certain amount of revenue or transactions in the state, regardless of physical presence.
- Contractual presence: Having a contract with a client in the state.
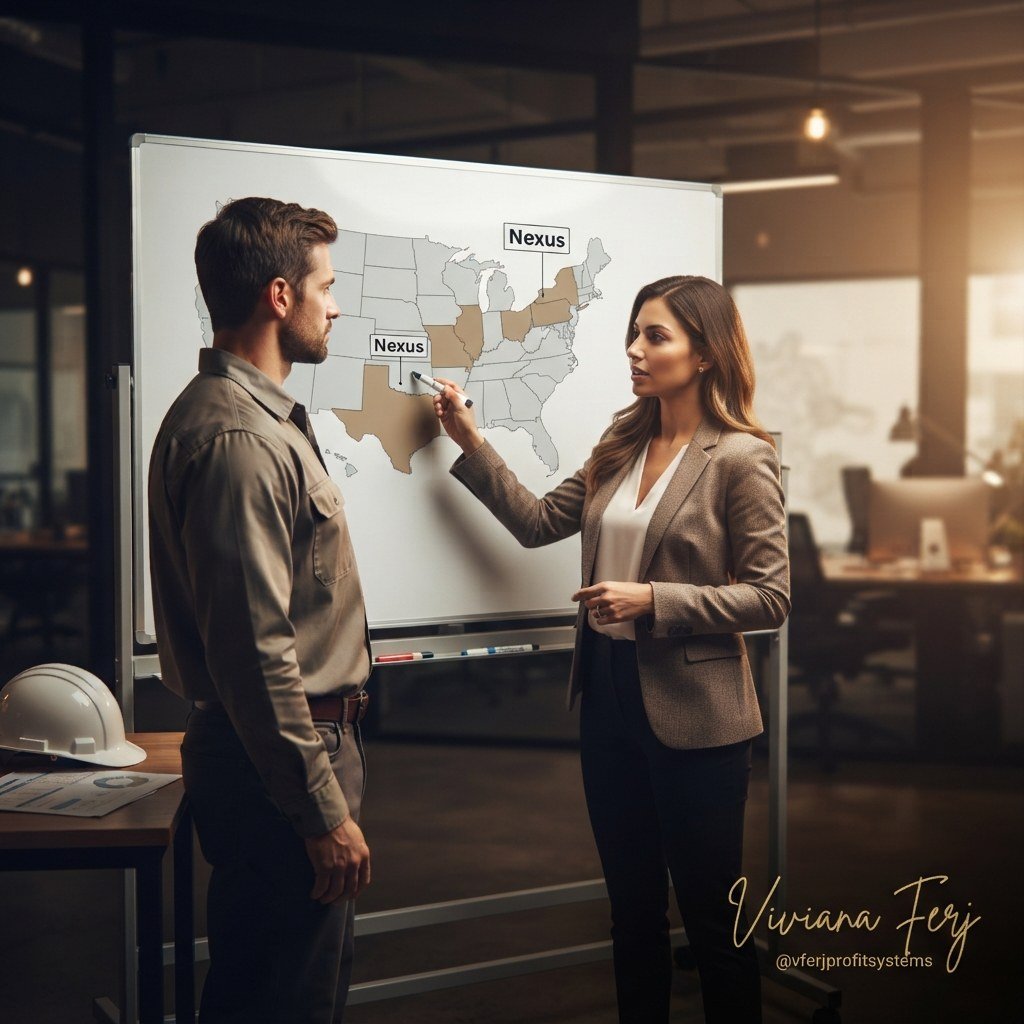
The Risks of Ignoring Multi-State Tax Obligations
- Back taxes and penalties: States can assess back taxes, interest, and penalties — sometimes going back years.
- Audit exposure: Once you're on a state's radar, you're more likely to be audited.
- Bonding impact: Tax liens can reduce your bonding capacity — or eliminate it entirely.
- Reputational damage: A tax lien is public record. It can affect your reputation with clients and sureties.
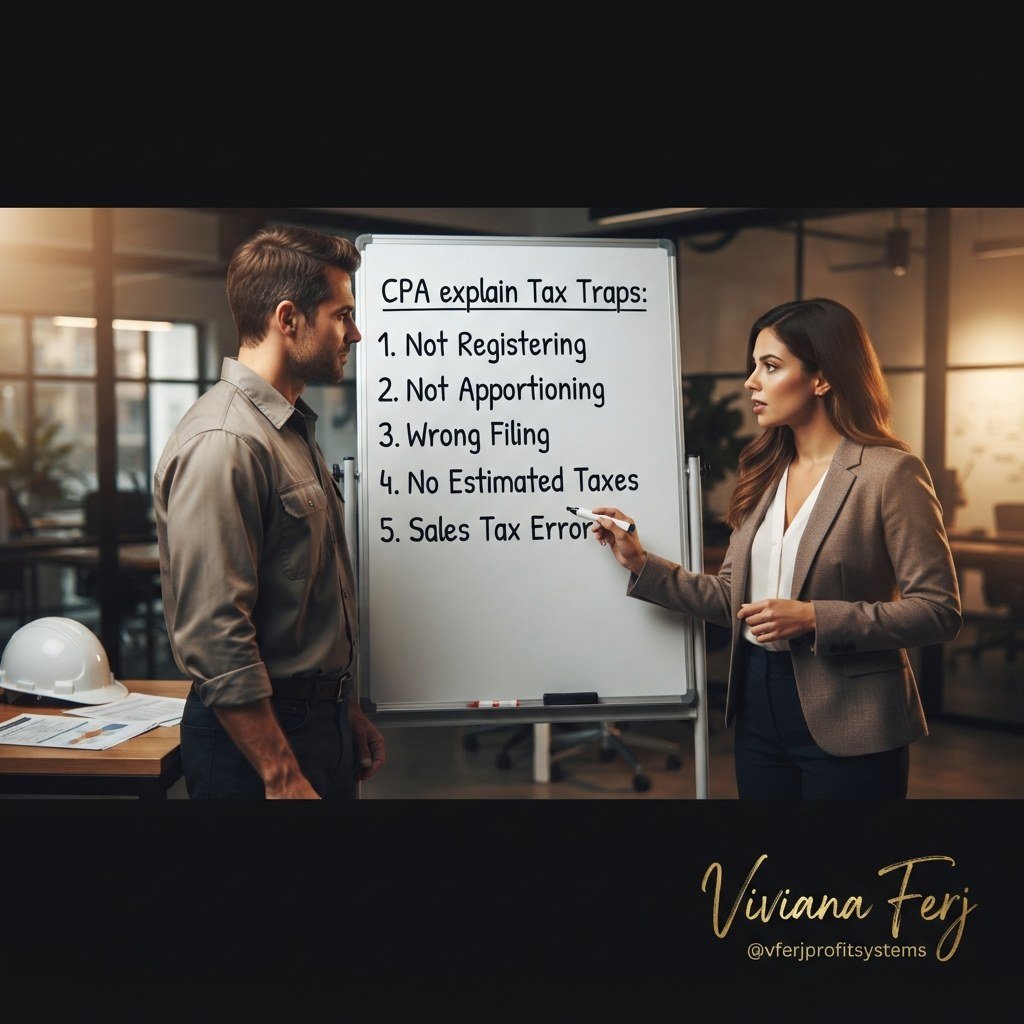
Common Multi-State Tax Traps for Contractors
- Working in a state without registering: Many states require contractors to register with the Secretary of State before they can work there.
- Not apportioning income correctly: Income must be apportioned among states based on factors like revenue, payroll, and property.
- Filing in the wrong state: Some states require separate filings; others allow consolidated filings. Getting it wrong can trigger an audit.
- Not paying estimated taxes: States often require estimated tax payments if you expect to owe more than a certain amount.
- Sales tax misclassification: Some states tax construction materials; others exempt them. Misclassification can lead to significant penalties.
How to Manage Multi-State Tax Risk
- Determine where you have nexus: Review your active projects, employees, and equipment. Identify every state where you have a presence.
- Register in each state: Register with the Secretary of State and state tax agency before you start work.
- Apportion income correctly: Use the state's apportionment formula to determine how much of your income is taxable in each state.
- File returns on time: Even if you owe no tax, file a return. States often require zero returns.
- Work with a multi-state tax specialist: Multi-state tax is complex. A specialist can help you navigate the rules.
How Multi-State Tax Exposure Affects Your Bonding
When a surety evaluates your bonding capacity, they look at your tax compliance. Tax liens, delinquent filings, and outstanding tax liabilities are all red flags. A surety won't bond a contractor who has unresolved tax issues in multiple states.
Frequently Asked Questions
How do I know if I have nexus in a state?
If you have employees, equipment, or a job site in the state — or if you generate revenue there — you likely have nexus. Consult a tax professional to be sure.
Can I be taxed in a state where I don't have an office?
Yes. Physical presence isn't the only factor. Economic presence — revenue or transactions — can also create nexus.
What's the penalty for not filing in a state?
Penalties vary by state. They typically include a percentage of the tax owed, plus interest, and can add up to significant amounts.
How do I apportion income among states?
States use formulas that consider revenue, payroll, and property. The specific formula varies by state.
Take This to a Full Diagnostic of Your Operation
- Real profitability per job, not just company-wide
- Multi-state tax exposure and compliance
- Tax provision and multi-state exposure
- Bonding capacity and subcontractor risk
Get These Insights Straight to Your Inbox
A new article on construction finance every month — no spam, unsubscribe anytime.