Sales Tax in Construction: Rules That Vary by State
Sales tax rules for contractors vary dramatically from state to state. Getting them wrong can cost you penalties — and your bonding capacity. Here's what you need to know.
The State-by-State Puzzle
Sales tax is one of the most complex areas of construction tax — and it's made more difficult by the fact that rules vary dramatically from state to state.
In some states, construction materials are taxable. In others, they're exempt. In still others, it depends on whether the contractor is the "owner" of the materials or the "consumer." And to make it more complicated, states often have different rules for residential vs. commercial construction.
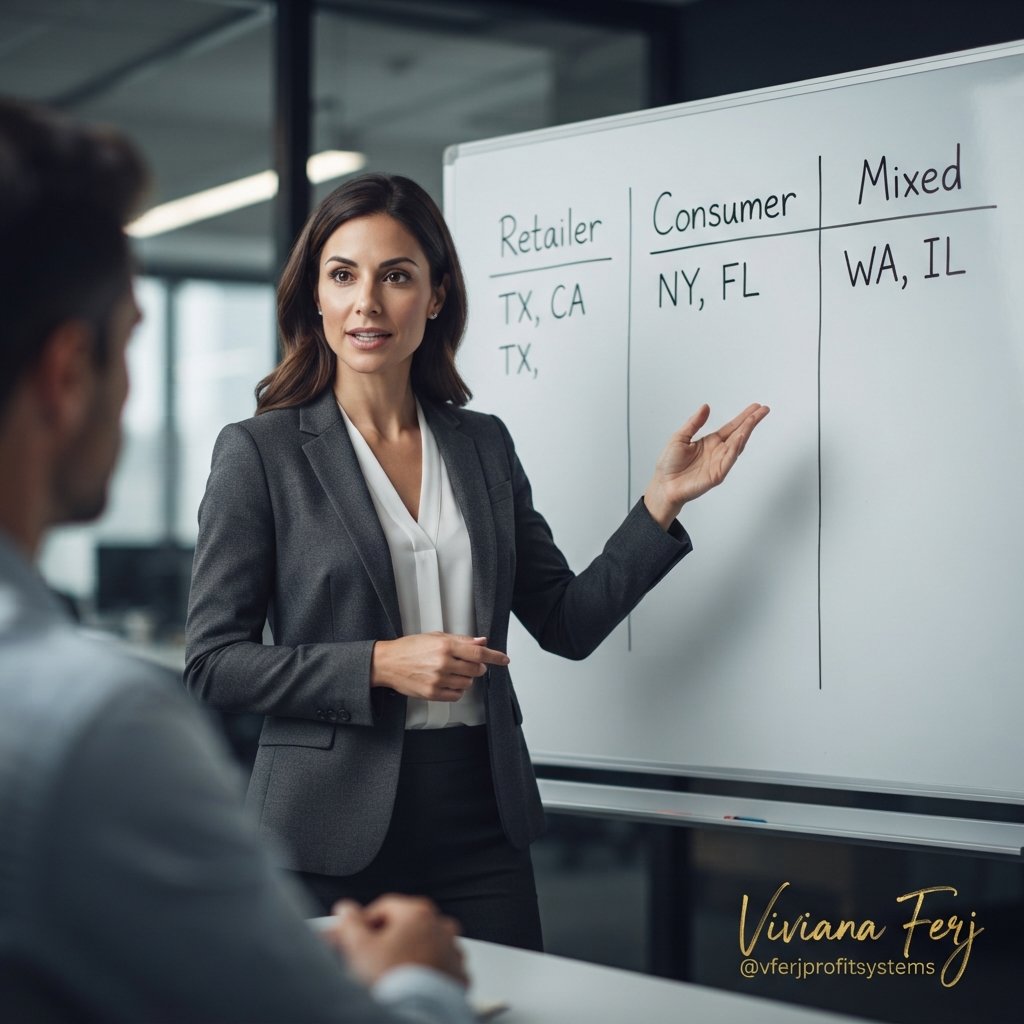
Three Common Sales Tax Models for Construction
- Retailer model: The contractor buys materials tax-free (using a resale certificate) and charges sales tax to the client. Common in states like Texas and Florida.
- Consumer model: The contractor pays tax on materials at the time of purchase and does not charge sales tax to the client. Common in states like California and Arizona.
- Mixed model: The contractor pays tax on materials for some types of projects and charges tax for others — often depending on whether the project is residential or commercial.
Common Sales Tax Mistakes
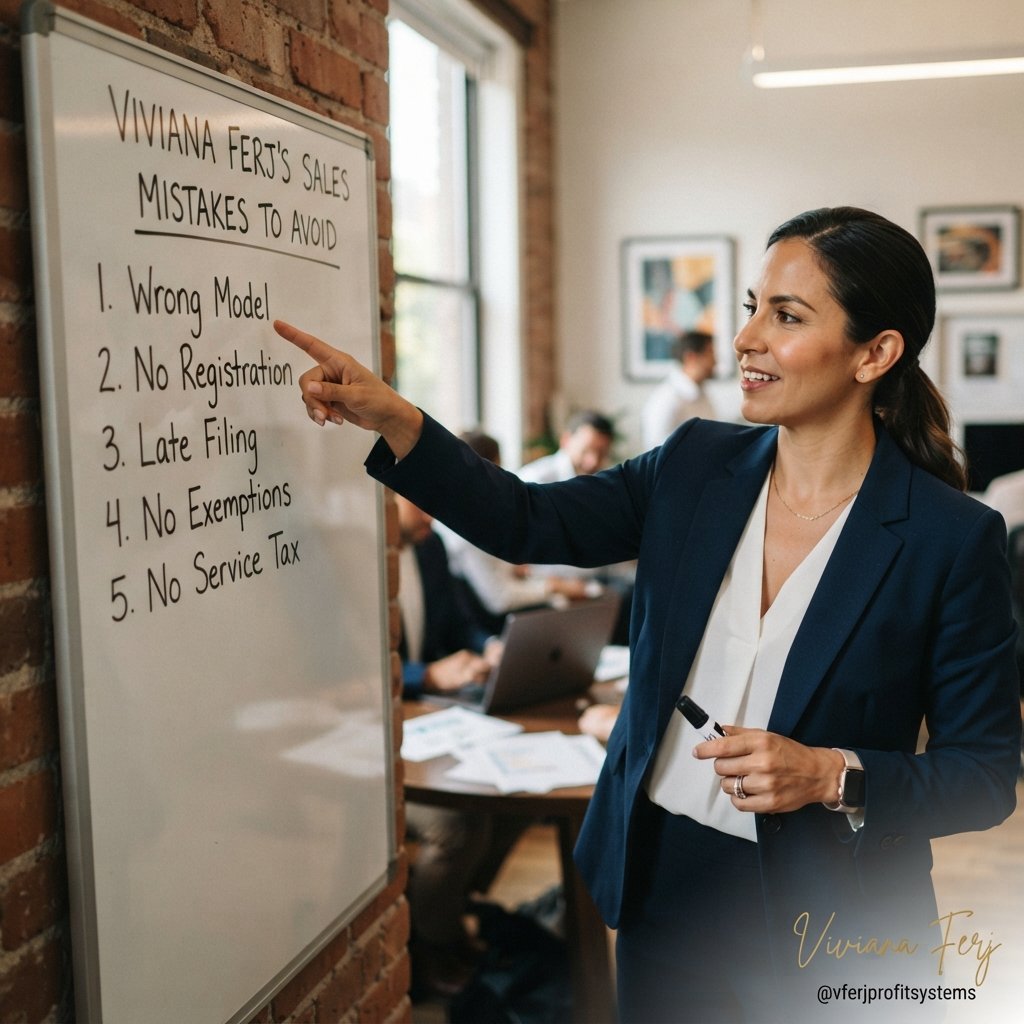
- Applying the wrong model: Assuming the rules from your home state apply everywhere.
- Not registering in the state: If you're working in a state, you need a sales tax permit — even if you don't owe tax.
- Filing late or not at all: States expect sales tax returns even if you owe zero.
- Not tracking exemptions: Some projects are exempt from sales tax — but you need the right documentation.
- Not charging tax on services: Some states tax construction services; others don't.
State-by-State Examples
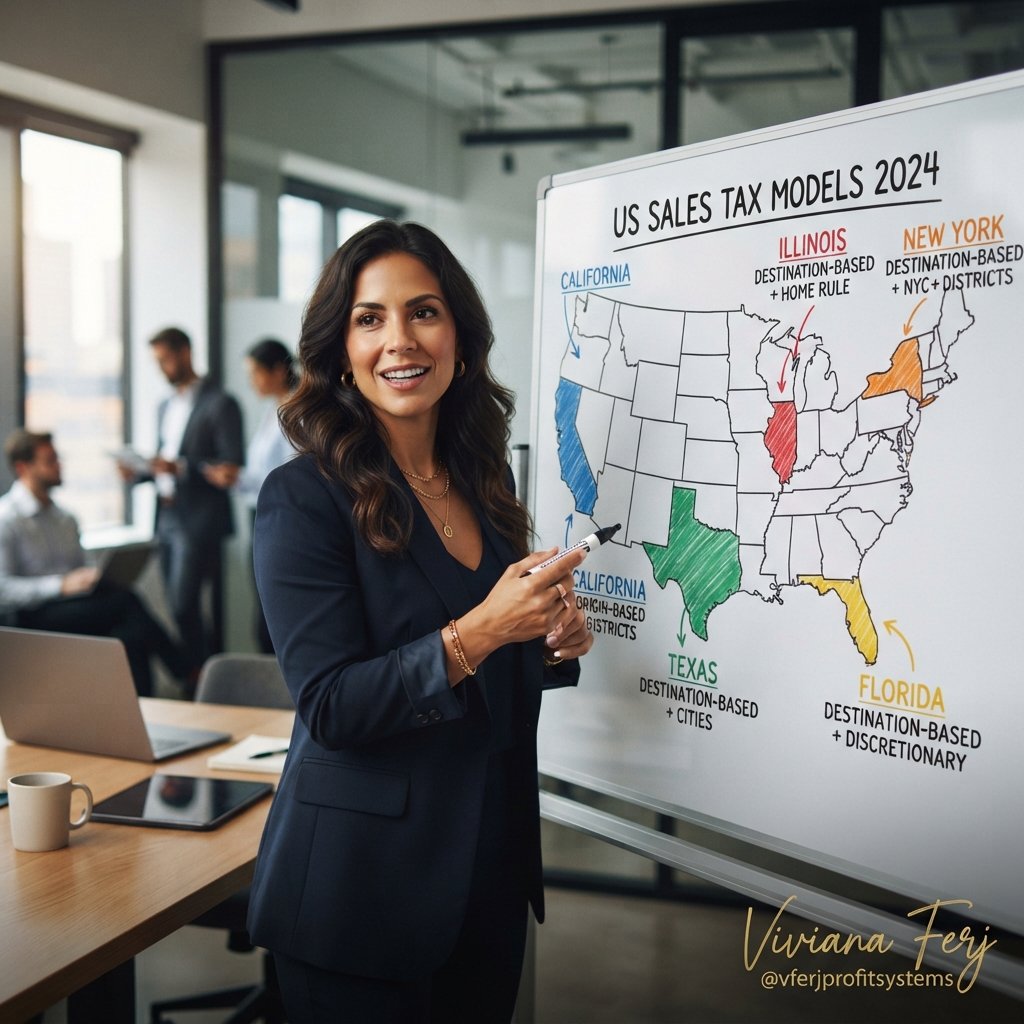
- California: Consumer model. Contractors pay tax on materials and don't charge sales tax to the client. Exemptions exist for some residential projects.
- Texas: Retailer model. Contractors buy materials tax-free and charge sales tax to the client. Labor is generally not taxable.
- New York: Mixed model. Materials are generally taxable, but the tax can be passed to the client on some projects.
- Florida: Retailer model. Contractors buy materials tax-free and charge sales tax to the client.
- Illinois: Consumer model. Contractors pay tax on materials and don't charge sales tax to the client.
The key takeaway: you need to know the rules in every state where you work.
How to Stay Compliant
- Register for a sales tax permit: Before you start work in a state, register with the state's tax agency.
- Understand the model: Determine whether you're operating under the retailer, consumer, or mixed model.
- Track exemptions: If a project is exempt, get the documentation — and keep it.
- File on time: Even if you owe zero, file the return. States track compliance.
- Work with a sales tax specialist: Sales tax is one of the most audited areas in construction. A specialist can help you navigate the complexity.
How Sales Tax Compliance Affects Your Bonding
When a surety reviews your bonding capacity, they look at your tax compliance. Sales tax liens, delinquent filings, and outstanding tax liabilities are all red flags. A surety won't bond a contractor who has unresolved sales tax issues in multiple states.
Frequently Asked Questions
Do I need a sales tax permit in every state?
Yes — if you work in a state, you need a sales tax permit, even if you don't owe tax.
Is labor taxable in construction?
It depends on the state. Some states tax construction labor; others don't. Some tax it only for certain types of projects.
Can I use my home state's resale certificate in another state?
No. You need a resale certificate issued by the state where you're working.
What happens if I don't file a sales tax return?
States can assess penalties and interest — and they can place a lien on your business, which affects your bonding capacity.
Take This to a Full Diagnostic of Your Operation
- Real profitability per job, not just company-wide
- Sales tax compliance and exposure
- Tax provision and multi-state exposure
- Bonding capacity and subcontractor risk
Get These Insights Straight to Your Inbox
A new article on construction finance every month — no spam, unsubscribe anytime.